

Airtel: Recharge, Bank & Loans analysis by Appwee
I usually judge a finance app by one practical question: does it remove a small daily annoyance without creating a bigger one? With Airtel: Recharge, Bank & Loans, the answer depends largely on whether you already use Airtel services. The app brings mobile recharge, bill payments, UPI-related payments, rewards, banking tools, and loan-related access into one finance-focused place. That combination is its central appeal, but it also shapes its limitations.
My experience with it is best described as convenient rather than revolutionary. Instead of moving between a separate recharge app, a payment app, and a banking application, I can begin with one Airtel account and handle several routine money tasks from the same environment. For an Airtel customer who wants fewer apps and a familiar service provider, that is a meaningful advantage. For someone looking only for a neutral payment wallet or a full-featured bank, the decision is less straightforward.
The application is free and is developed by Airtel. It is available to everyone from a content-rating perspective, while its current version is 4.149.2 and it requires Android 7.0 or newer. Its scale is considerable: it has passed 500 million installs, with a 4.0 average from around 7.9 million ratings. Those figures suggest that the app is not a niche utility, but popularity alone does not guarantee that its mix of financial tools will suit every user.
One place for recurring payments and everyday finance
The capability that matters most
The strongest capability is the way Airtel connects routine payments with its wider financial services. A mobile recharge is not treated as an isolated task; it sits alongside bill payments, UPI activity, rewards, banking features, and loans. That matters because many people do not think about these jobs as separate categories. They simply want to top up a phone, settle a bill, send money, or check a financial option before moving on.
Articles related to Airtel: Recharge, Bank & Loans
I found this especially useful when the payment need started with Airtel itself. If my immediate goal was to recharge a number, the app made sense as a first stop. The same is true for users who already recognize Airtel as their telecom provider and prefer to keep related account activity in one place. The app feels less like a specialist banking product and more like a service hub with finance built into it.
That distinction is important. A specialist UPI application may feel cleaner if all I want is person-to-person payment. A traditional bank app may offer a deeper view of accounts and formal banking tasks. Airtel’s advantage is the bridge between telecom routines and money movement. Its usefulness grows when those two parts of your life overlap.
What the combined approach changes
Putting these tools together can reduce the number of decisions I make during a busy day. I do not have to remember which app handles a recharge and which one handles a bill. I can start from the Airtel environment and look for the relevant financial action there. This is a small improvement, but repeated small improvements are exactly where a finance app earns its place on a phone.
The combined design also makes rewards more relevant than they would be in a standalone payment tool. A reward attached to a routine recharge or bill payment can feel like a useful extra rather than a separate loyalty program I need to remember. Still, I would treat rewards as a bonus, not as the reason to choose the app. Their value depends on the activity I already perform and on whether the available offer is useful at that moment.
The banking and loan sections broaden the app’s role, but they also require more attention from the user. A recharge is a quick, familiar transaction. Financial products deserve slower reading and careful comparison. I would not move from a simple payment screen into a borrowing decision just because both options appear in the same application.
How it works in a normal payment routine
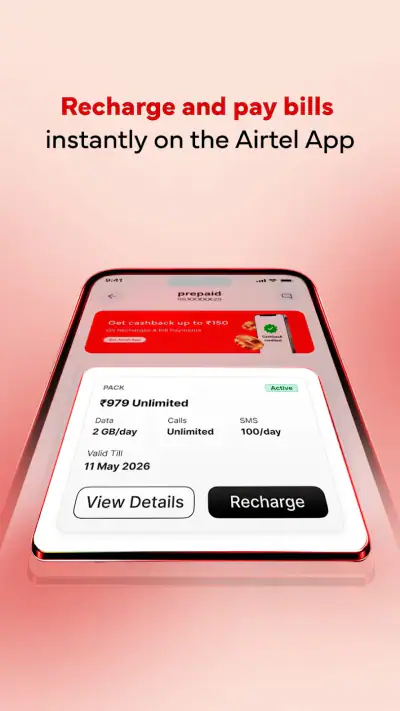
A realistic use case is a busy morning when a phone needs a recharge and a household bill is due later the same day. I can open the app, deal with the immediate mobile task, and then return to the finance area for the bill. The benefit is not that either payment is impossible elsewhere; it is that the two errands are grouped together in a way that matches how I organize my day.
For a first-time user, I recommend setting up the app when there is no urgent payment waiting. Explore the recharge, bill, UPI, rewards, banking, and loan areas calmly. That initial tour helps prevent the common mistake of opening a finance app under pressure and selecting the first visible option without understanding where the transaction is going.
I also prefer checking the recipient, number, biller, and final amount immediately before confirming. This is good practice anywhere, but it matters more in an app that combines several payment types. A familiar interface can make a transaction feel automatic, and automatic behavior is exactly when an incorrect number or account can slip through.
Where UPI fits into the experience
UPI gives the app a broader role than a simple telecom recharge tool. It means the application can participate in everyday payments beyond Airtel-specific services. That is useful for people who want one familiar starting point for recharges, bills, and UPI activity rather than maintaining several finance apps.
However, I would not assume that a broad feature list automatically makes it the best UPI choice. Users who send money frequently may prefer an app designed around fast payment history, contacts, and a minimal transaction flow. Airtel is more appealing when payment is one part of a wider relationship with the provider, not when UPI is the only thing that matters.
A practical habit is to separate convenience from financial records. I use the app for the transaction, but I still pay attention to confirmation details and keep my own awareness of recurring bills. A single app can simplify access without replacing personal budgeting. That is particularly important when rewards or promotional elements make the screen feel busier than a basic payment form.
Rewards: useful when they stay in the background
The rewards element can make ordinary activity feel more worthwhile, but I think it works best when I do not chase it. Changing a payment decision solely to obtain a reward can lead to unnecessary spending or a less suitable payment method. The sensible approach is to complete the task I already needed and then regard any reward as an extra.
I would also read the conditions attached to an offer before relying on it. A reward is not the same thing as an immediate reduction in the amount being paid, and the practical value can depend on how it is delivered or used. The app is more trustworthy as a daily finance tool when I treat promotional benefits with the same care I give any other financial detail.
The best scenario for Airtel
The app is at its best for an Airtel customer who wants to combine telecom management with regular financial errands. Imagine a user who recharges a family number, pays household bills, occasionally uses UPI, and likes having rewards visible in the same account. For that person, Airtel can replace a scattered routine with a more coherent one.
This scenario also explains why the app may feel less valuable to someone who rarely uses Airtel services. If mobile recharge is not part of your normal life, one of the app’s most natural entry points disappears. You may still find the banking or payment tools useful, but the reason to keep this particular combination becomes weaker.
I see another good fit in households where one person handles several recurring payments. The benefit is organizational: the user can begin with the service they know and then move through related finance tasks. I would still avoid sharing login details or handing over a device casually, because convenience should not come at the expense of control over financial activity.
Banking and loans require a different mindset
The banking and loan sections make the app more ambitious, but they should not be approached with the same speed as a recharge. Whenever borrowing is involved, I would examine the amount, repayment schedule, total cost, eligibility conditions, and consequences of missing a payment before proceeding. The presence of a loan option inside a familiar app does not make borrowing automatically suitable.
This is one of the app’s most important trade-offs. Its unified design can make financial services feel accessible, which is helpful for discovery, but accessibility can also encourage rushed decisions. I would use the app to investigate an option, then compare it with alternatives and my own budget before accepting anything. If I need detailed financial planning, a bank adviser or a dedicated budgeting tool may be more appropriate.
The same caution applies to banking features. A convenient overview is useful for everyday management, but users with complicated finances may need a deeper account structure, stronger analysis, or specialized investment tools. Airtel works best as an accessible daily finance layer, not necessarily as the only place I manage every part of my financial life.
Trade-offs in a broad finance app
The biggest weakness is the possibility of visual and mental clutter. Recharges, bills, UPI, rewards, banking, and loans all compete for attention. A user who wants one quick payment may need to scan past several categories before reaching the right action. That is the price of having a multi-purpose service hub.
There is also a trust trade-off. I may be comfortable using a telecom provider for a recharge, but banking and borrowing involve a higher level of scrutiny. The broader the app becomes, the more important it is for me to understand which service I am entering and what commitment follows from it. Familiar branding should not replace careful reading.
Another limitation is that convenience can encourage dependence on one ecosystem. If I keep all payment habits inside one provider’s application, switching later may feel inconvenient even when another service offers a better experience for a particular task. I prefer to keep alternatives available, especially for important payments, rather than assuming one app must handle everything.
Performance and usability can also vary with device age, network quality, and the number of services presented. The Android requirement of version 7.0 or newer makes the app accessible to many users, but an older phone may still feel less comfortable with a feature-rich finance application than a newer device. I would test the core payment flow before making it my only method for urgent transactions.
Who gains the most from using it
I would recommend Airtel most strongly to people who already use Airtel and want a single place for recharges and related money tasks. It is also a sensible option for users who value convenience over having a separate specialist app for every function. The free price makes trying it low-risk, provided the user remains attentive to transaction details and financial commitments.
It is less suitable for someone seeking a pure banking experience, advanced budgeting, or a distraction-free UPI interface. If your priority is detailed financial analysis, a dedicated banking or budgeting product may be better. If you only need occasional mobile recharge, the extra sections may add more complexity than value. And if you are considering a loan, the app should be a starting point for comparison, not the final reason to borrow.
The app’s large audience—more than 7.9 million ratings and roughly 8.8 thousand written reviews—shows that many people have made it part of their routine. I read that reach as evidence of practical usefulness, not as proof that every feature will suit every user. The right question is whether its Airtel-centered organization matches the way you already pay.
My practical recommendation
I would install it first for the recharge and bill workflow, then decide whether the UPI, rewards, banking, and loan areas genuinely improve my routine. That order matters. It lets me judge the app by a concrete daily need instead of being distracted by the breadth of its menu.
Before relying on it, I would complete a low-pressure transaction, inspect the confirmation carefully, and learn where payment history and support options are located. I would also keep a separate note of recurring bills and avoid treating rewards as guaranteed savings. These habits make the app more useful while limiting the risks that come from rushing through a broad financial interface.
After using it this way, my view is positive but specific. Airtel is strongest as a convenient bridge between mobile services and everyday payments. It can simplify life for the right Airtel customer, especially when recharges, bills, and UPI belong to the same routine. Its wider banking and loan tools add reach, but they also demand more judgment. I recommend it to users who want that connected ecosystem; I would point everyone else toward a more specialized finance app when depth, simplicity, or independent comparison matters more than convenience.
Gallery
Airtel: Recharge, Bank & Loans Pros and Cons
- Recharge mobile
- DTH
- and broadband services from one app.
- Airtel Payments Bank simplifies everyday digital transactions.
- Loan services and financial tools are available in one place.
- Bill payment reminders can help users avoid missed due dates.
- The interface is generally familiar to existing Airtel customers.
- Some services may only be available to eligible Airtel users.
- Loan approval
- limits
- and interest rates depend on personal eligibility.
- Payment failures can occasionally require repeating the transaction.
- The app may promote Airtel products and partner offers frequently.
- Availability of banking features can vary by region and account status.
Airtel: Recharge, Bank & Loans Frequently Asked Questions
What is Airtel: Recharge, Bank & Loans used for?
Airtel: Recharge, Bank & Loans is a multi-purpose mobile services app designed for Airtel customers. From the app, users can recharge prepaid numbers, pay postpaid and broadband bills, manage selected Airtel services, and access financial features such as Airtel Payments Bank and eligible loan-related services. The exact options available may vary depending on your country, account type, mobile plan, and Airtel’s current offerings.
Can I recharge mobile numbers and pay bills through the Airtel app?
Yes. The app generally allows users to recharge Airtel prepaid connections and pay bills for services such as postpaid mobile, broadband, or digital television where supported. You can usually choose a plan or enter a custom amount, review the transaction details, and complete payment using available methods such as cards, UPI, net banking, or supported wallets. Always verify the number and amount before confirming.
Is Airtel Payments Bank available to every user?
Airtel Payments Bank features are not necessarily available to every person who downloads the application. Eligibility can depend on your location, mobile number, identity verification, age, regulatory requirements, and the services currently offered in your region. Account opening and certain transactions may require official KYC documents or additional verification. Check the in-app terms carefully before submitting personal or financial information.
Can I apply for a loan through Airtel: Recharge, Bank & Loans?
The app may display loan or credit offers from Airtel or its partnered financial institutions, but approval is not guaranteed. Eligibility, loan amount, interest rate, repayment period, processing charges, and documentation requirements can differ between users. Before accepting an offer, read the lender’s agreement, understand the total repayment cost, and confirm which regulated provider is issuing the loan. Avoid treating promotional eligibility messages as final approval.
Is Airtel: Recharge, Bank & Loans safe to download and use?
The official app can provide security features such as account authentication, transaction confirmations, and protections for supported payments, but users should still take normal precautions. Download it only from the official Google Play Store or Apple App Store, check the developer name, and avoid unofficial APK files. Never share your OTP, PIN, password, or banking credentials with anyone, including callers claiming to represent Airtel.














